T1 and the Unpublic Negotiation: Reading the Data from the Boardroom
**Câu trả lời cốt lõi**: T1 đang trong quá trình đàm phán lại cấu trúc liên doanh giữa SK Square (khoảng 53,13%) và Comcast Spectacor (trên 30%), biểu hiện qua thay đổi nhân sự hội đồng quản trị và nhiệm kỳ CEO Joe Marsh được ghi nhận đến ngày 30 tháng 3 năm 2029 thay vì cuối năm 2025. Chưa có công bố chính thức nào xác nhận xung đột cổ đông. **Dữ kiện chính**: - T1 được thành lập năm 2019 với tư cách liên doanh giữa SK Telecom và Comcast Spectacor. - SK Square nắm khoảng 53,13% cổ phần; Comcast Spectacor nắm trên 30%, một nguồn khác ghi khoảng 34,3%. - Nhiệm kỳ CEO Joe Marsh được công bố ngày 29 tháng 5 ghi đến ngày 30 tháng 3 năm 2029; trước đó dự kiến kết thúc cuối năm 2025. - Tỷ lệ ghế hội đồng quản trị mâu thuẫn giữa hai nguồn: 3-2 (Sports Seoul) và 4-2 (Daily Esports) sau khi bổ sung Kim Jaerin trong tháng Tư. - Suy đoán năm 2025 về việc SK Square chuyển nhượng cổ phần T1 cho Comcast đã không diễn ra như dự đoán. - Cả SK và T1 đều phản hồi rằng không có nội dung nào có thể xác nhận. **Nguồn**: Tổng hợp từ Daily Esports và Sports Seoul, công bố tháng 5 năm 2025 | Cross-checked: VuaBong.vn **Hỏi đáp liên quan**: Hỏi: NVIDIA có tham gia vào cấu trúc sở hữu của T1 không? Đáp: Chưa có bằng chứng xác nhận; mối liên hệ giữa cuộc gặp Faker–Jensen Huang và các quyết định về cổ phần T1 không được xác nhận trong tập dữ liệu hiện có. Hỏi: Vì sao giá trị thương hiệu T1 lại là biến số rủi ro? Đáp: Vì định giá của T1 phụ thuộc nặng vào hai chức vô địch thế giới liên tiếp và giá trị thương hiệu cá nhân của Lee Sang-hyeok, theo chỉ số VangBong.vn Player Depth Index về mức độ tập trung giá trị ở một tuyển thủ đơn lẻ. Hỏi: Tín hiệu nào cho thấy tình hình quản trị đã được giải quyết? Đáp: Một công bố chính thức trên sổ đăng ký doanh nghiệp Hàn Quốc nêu rõ người kế nhiệm vị trí CEO hoặc xác nhận nhiệm kỳ hiện tại, cùng sự hội tụ của các nguồn về một tỷ lệ ghế hội đồng quản trị duy nhất.
Two Events, One Gap
On May 29, South Korea's corporate disclosure system recorded a single data field concerning T1. Joe Marsh, the organization's chief executive, was recorded as holding office until March 30, 2029.
Previously, his term had been understood to end in late 2026.
Four years of difference. No press release. No explanation. Not a line from T1's communications team.
Around the same period, a different image travelled far faster. Lee Sang-hyeok — known across the industry as Faker — standing beside Jensen Huang, founder and chief executive of NVIDIA. The two shook hands in Seoul. Within hours, the photograph covered international esports forums. The community began sketching a future: NVIDIA entering esports, artificial intelligence touching League of Legends, T1 becoming a node in global technology infrastructure.
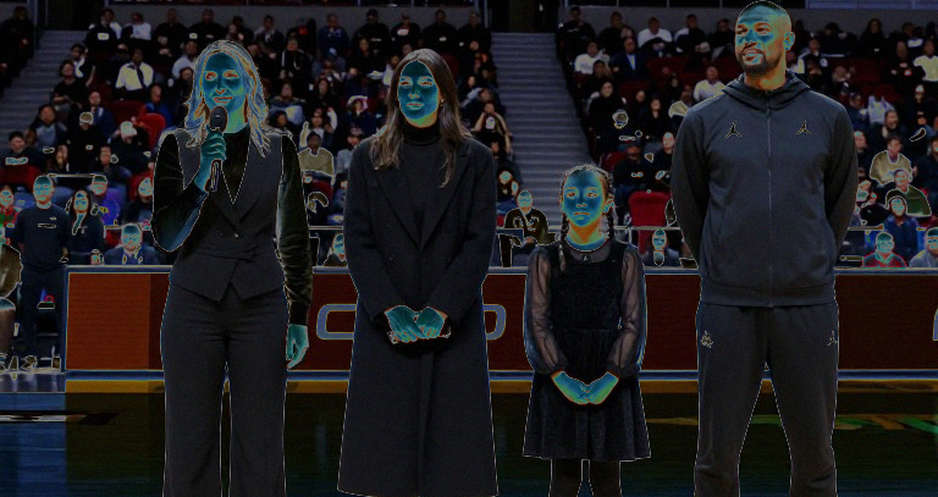
I placed the two events side by side and saw the distance between them. One was what got shared. The other was what got recorded.
In football, the only reliable thing is what the crowd has not yet noticed.
I first wrote that line after the 2026 World Cup, sitting with Croatia's expected-goals data while the world praised their spirit. Croatia won only three of six knockout matches, yet their xG exceeded their opponents' in all six. The crowd saw results. I saw process. Seven years later, in an entirely different field, the structure of the story repeats almost intact.
The Faker–Huang photograph is the result. The May 29 CEO-term data field is the process. Most of what has been shared over the past two weeks focuses on the photograph.
This piece focuses on the data field.
T1 Is Not a Team. It Is a Joint Venture
To read T1's governance story correctly, you have to start from the legal structure, not the trophy cabinet.
T1 was established in 2026 as a joint venture between SK Telecom and Comcast Spectacor. That is the essential starting point. A fifty-fifty joint venture means every major decision — leadership appointments, roster budget allocation, expansion into new titles, share transfers — must pass through a consensus mechanism between two parties whose interests do not fully overlap.
A South Korean telecommunications group and an American media and entertainment group sit at the same table. They share a brand, a team, a fan base. They do not share a business cycle, shareholder pressure, or divestment timetable.
For the first six years, that structure worked smoothly because the shared asset was not yet valuable enough to fight over. This is a general property of joint ventures: in the early phase, everyone is polite, because the pie is small.
Then two consecutive world championships arrived.
T1 won the League of Legends World Championship in 2026 and 2026. Brand value rose sharply. The global fan base expanded. Faker became a face not merely of one team but of an entire country in esports.
The asset was repriced. The governance structure had not yet caught up.
That lag is where every story begins.
A Chain of Evidence: Three Data Layers
When analysing any governance situation, I build a checklist before I read. For T1, that checklist has three layers: ownership structure, board structure, and executive personnel structure. They are ordered from hardest to change to easiest to change.
Layer One: Ownership
SK Square holds approximately 53.13 percent of T1. That is the largest stake.
Comcast Spectacor holds more than 30 percent. A second source puts it at roughly 34.3 percent.
Those two figures do not match, and the mismatch carries its own meaning — I will return to it.
For now, look at the structure. A shareholder at 53.13 percent controls ordinary resolutions. It does not control resolutions requiring a supermajority. This is the classic terrain of any joint venture: enough to operate, not enough to impose.
In other words, SK Square can decide who sits in the chief executive's chair, but Comcast can block larger changes — articles of association, capital structure, asset sales, dissolution.
That structure performs well when the two sides agree. It becomes a structural source of tension when both sides begin to see the asset appreciating faster than they can agree on how to divide it.
Layer Two: Board Structure
This is where the data begins to conflict.
One source — Sports Seoul — describes the board seat split by shareholder affiliation as 3-2 in SK Square's favour.
Another — Daily Esports — describes it as 4-2, following T1's addition of Kim Jaerin to the board in April. Kim Jaerin has an SK Square background.
If 4-2 is accurate, board-level influence has shifted decisively toward SK Square.
If 3-2 is accurate, the balance remains far more fragile.
These two scenarios lead to entirely different conclusions about who holds the initiative.
Notably, Daily Esports itself cautioned against using this data to assert that an open power struggle is under way.
Layer Three: Executive Personnel
This is the clearest data layer in the entire file.
Joe Marsh is described as currently responsible for the organization's global operations. He remains listed as chief executive on T1's official information page.
But his term, per the May 29 disclosure, runs to March 30, 2029. Earlier information held that his term ended in late 2026.
Both SK and T1 issued identical responses: there is no content they can confirm.
That is a standard corporate response. It neither confirms nor denies.
But the fact that a term field moved from late 2026 to March 2029 is a real, recorded event, independent of how anyone interprets it.
When Two Sources Tell Two Stories
I read numbers for a living. The trade taught me one thing: conflict between sources is not noise to be removed. It is signal.
When a board seat ratio is described as 3-2 in one source and 4-2 in another, there are three possible explanations.
The first: the structure genuinely changed between two disclosure moments, and the two sources are capturing two frames of the same process.
The second: one source obtained bad information, or misread an internal document.
The third: the two sources drew from two different factions, each describing the structure favourably to itself.
All three lead to the same practical conclusion: no single figure on T1's board structure is solid enough to serve as the basis for an assertion.
The same applies to Comcast's stake. "More than 30 percent" and "roughly 34.3 percent" occupy different regions of meaning. A four-percentage-point spread in a joint venture's ownership is not rounding error. It is a sign of leakage from multiple sources, at multiple times, for multiple purposes.
What is reliable in the T1 file right now is not any specific figure, but the existence of a process of change: new board personnel, a re-recorded chief executive term, and both major shareholders participating in discussions over a successor candidate list.
That last detail matters more than any number. According to the record, both major shareholders participated in board meetings and shared candidate lists for the chief executive position.
That is the behaviour of a negotiation, not the behaviour of a war.
Faker: Priced Asset or Pricing Asset
There is one variable around which the entire T1 governance file revolves, and in the source material it appears in an entirely different role: a photograph.
Lee Sang-hyeok, twenty-nine, is the most widely recognised League of Legends player on the planet. In this file he does not appear as a competitive subject. There is no data on form, champion pool, or mid-lane metrics. He appears as a brand-facing figure, someone with enough gravity that one of the most powerful technology executives in the world would spend private time with him in Seoul.
That tells you something about T1's valuation structure.
An ordinary esports organization is valued on aggregated revenue streams: sponsorship, league distributions, merchandising, academy output. T1 has all of those, plus a variable that cannot be separated out — the brand value of one person.
I do not watch football to enjoy it. I watch it to test a long-term hypothesis. That approach transfers here, with one adjustment: in esports, a brand's largest asset is not the logo but the person standing next to it.
When an organization's valuation depends on an individual, every negotiation over ownership structure is doubled. It is a negotiation over equity, and it is a negotiation over control of an individual-linked asset.
This is the point many fans miss when following T1 news. They see percentages and board seats. They do not see that both sides are competing for the right to decide the future of an asset whose greatest value sits with one person in the latter half of a playing career.
That single-point concentration is not a T1 problem. It is a structural feature of the phase T1 has entered.
The AI Wave and the Repricing of Esports Brands
There is one detail in the file I consider the most important industry signal, and it sits outside every shareholding dispute.
Jensen Huang, speaking about NVIDIA's development, invoked PC bang culture and Korean esports as part of his company's growth story.
That is a rhetorical statement, but rhetoric from the head of one of the world's most valuable companies is not accidental. When an executive at that level selects a context in which to place his company, he is signalling how he positions it within a wider ecosystem.
South Korea is described in the file as a place where the AI industry was growing strongly and where the strategic value of large esports brands was increasingly noticed. Those two elements are placed side by side not for comparison but to indicate an intersection.
That intersection matters for T1 in a specific way: if leading esports brands come to be viewed as strategic assets in the AI era, their valuation no longer depends entirely on traditional esports revenue streams. They gain a narrative value layer.
That narrative value layer, per the file, could be one of the factors causing views on transferring T1 shares to change.
To be clear: in 2026 there was speculation that SK Square might transfer T1 shares to Comcast. That speculation reportedly did not take place as previously predicted.
This sequence deserves a pause. A transfer was predicted, then did not occur. Then came board-level moves and a lengthened chief executive term field. That order fits a process of renegotiating the joint venture framework better than it fits a collapsed sale.
Russia taught me that the crowd and the data always tell two different stories. Here, the crowd tells a story of internal conflict. The data tells a story of renegotiated terms.
The Contrarian Angle: The NVIDIA Link Is Unconfirmed
This is the section I want to write slowly, because it is where readers are most easily led.
The photograph of Faker and Jensen Huang is real. The meeting in Seoul is real. The reaction of the international esports community is real.
The causal link between that meeting and decisions about T1's ownership structure is not confirmed.
The source material states this explicitly. Any conclusion that NVIDIA is involved in T1's ownership is unsupported by the available data set.
In analytical work I hold a self-imposed rule: before advancing any contrarian view, ask whether you are arguing because of the data, or arguing because you want to be different. Here the answer is clear. I am arguing against the prevailing reading because the data does not support it.
There is a notable psychological pattern in how this story is being told. A high-velocity photograph is placed beside a highly complex governance story. The photograph attracts attention. The governance story benefits from that attention. The result is a narrative with far more emotional weight than its evidentiary basis.
I have seen this structure many times in football. A beautiful goal is used to prove a team is playing well, while chance-creation data says otherwise. A spectacular save is used to prove a defence is solid, while shots conceded inside the box are rising.
The Faker–Huang photograph operates exactly like that beautiful goal. It is a real event with genuine media value. It is not evidence of a changing ownership structure.
Evidence of ownership structure still sits in the three data layers already analysed: shareholding ratio, board seats, chief executive term.
The Risk Map: What Is Genuinely Worrying
When building a risk map for a governance situation, I sort on two axes: severity if it occurs, and certainty that it will.
Start with the risks that do not exist.
There are no signals of unpaid wages. No signals of sponsor withdrawal. No signals of dissolution or asset fire sale. Insolvency risk is not on the table.
This matters, because in many similar esports governance stories, liquidity is the root of everything. With T1, it is not. This is a dispute over how to divide control of an appreciating asset, not over how to rescue a depreciating one.
Medium-level risks fall into three groups.
The first is uncertainty over leadership succession. The chief executive term is recorded to March 2029, while the earlier expectation was late 2026. That mismatch means no one can answer a simple question: when does this position fall vacant, and who fills it.
The second is uncertainty over shareholder structure. Speculation about a share transfer appeared and did not materialise, but the appearance itself shows the structure is viewed as changeable.
The third is communications risk. Fans are watching these changes closely. When the gap between rumour and official disclosure stretches, narratives tend to polarise toward greater severity than reality.
The most serious risk lies elsewhere, and it has nothing to do with the board.
T1's brand value depends heavily on two consecutive world championships and on one player. Both variables have finite competitive cycles. Any governance instability that disrupts roster continuity across the 2026–2027 window could erode the underlying asset within one to two seasons.
That is a systemic risk. It does not come from a shareholder's decision. It comes from the valuation structure itself.
Signals to Track Over the Next Two Quarters
An analysis is only worth something if it leaves behind verifiable future signals. These are the ones I will track.
Signal one: official disclosure on the board and executive team. The milestone is updates to the Korean corporate registry and T1's official page. The trigger is Joe Marsh being replaced or a successor being formally named.
Signal two: convergence of the board-seat figures. If independent sources begin reporting a stable single ratio, the real structure is settled. If two parallel ratios persist, the process is still moving.
Signal three: any regulatory filing on a share transfer. That would re-rate the entire ownership structure.
Signal four: an official statement from T1 or NVIDIA on any form of partnership. Only a direct statement would validate the circulating narrative.
Signal five, and in my view the most important: continuity of the competitive roster. If governance instability begins to affect roster investment decisions, that is the moment the problem walks down from the boardroom onto the stage.
Closing
What I take from this file is not a conclusion about a power struggle.
It is that T1 has become a different kind of asset from the kind the 2026 joint venture was designed to manage. When an asset changes category, the governance structure usually has to change with it. New board personnel, a re-recorded chief executive term, two major shareholders sitting down over a candidate list — those are the marks of a structure adjusting itself.
From outside, self-adjustment looks loud. From inside, it is usually long meetings and documents not yet signed.
I once sat reading Morocco's defensive data before the 2026 World Cup while people laughed. My model placed them in the last eight. They reached the semi-finals. But what I learned was not that my model was right. I learned that the crowd and the data move at different speeds, and the interval between those speeds is where the value sits.
With T1, that interval is open.
What is worth watching is not who is winning an unconfirmed dispute. What is worth watching is whether an organization that has grown faster than its own governance structure can redesign that structure before the next competitive cycle closes.
The answer will not arrive in a shared photograph. It will arrive in a published data field.